Two notices arrive at the same business during one week. Both look urgent and mention obligations, but sending them together to the accountant can leave part of the problem unattended. The first decision is to identify which authority issued each document, what it requests and which case file it needs. The email subject helps locate the document; it does not replace reading the official act.
The authority and subject determine the assignment
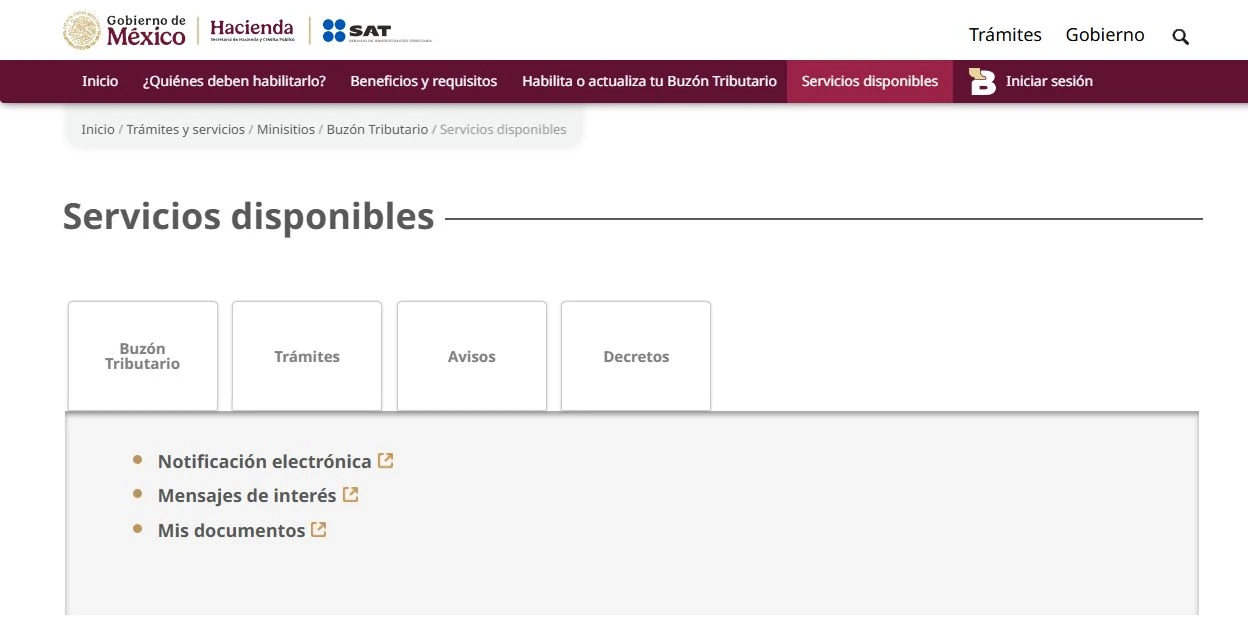
Publicación de InstagramMostrarOcultar
Original Fintax Instagram publication about notices from SAT and IMSS.
Article 38 of the Federal Tax Code (CFF) establishes requirements for administrative acts, including identifying the issuing authority, stating legal grounds and reasons, and expressing their object or purpose. Extract those details from the complete document. Then identify the period and the RFC tax identifier or employer registration it concerns. Two documents involving the same business do not necessarily have the same scope.
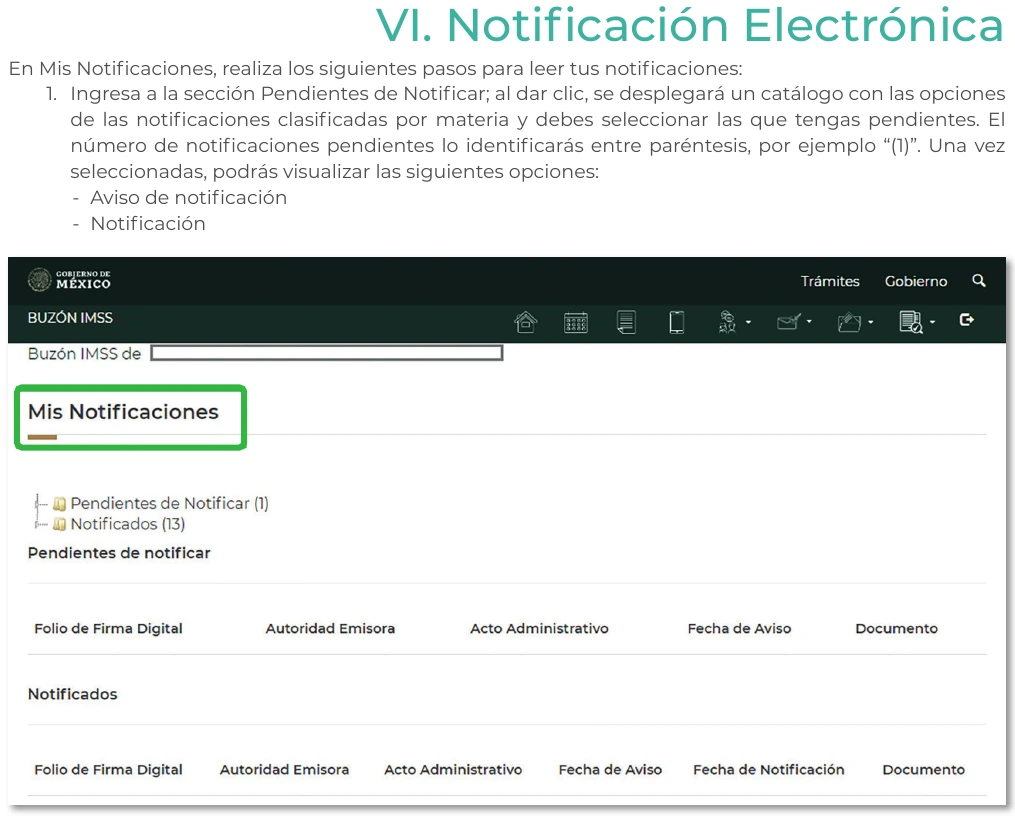
IMSS is an autonomous fiscal body; its procedures do not become SAT procedures. The Social Security Law (LSS) identifies Buzón IMSS in article 5-A, subsection XXIII. Article 9 provides for supplementary application of the CFF where compatible. Sharing tax rules therefore does not allow authorities, case files or submission channels to be merged.
Which file goes to which specialist
| Folder | Details that distinguish the case | Evidence to review | Recommended lead |
|---|---|---|---|
| A: SAT tax | Authority, RFC, subject and requested period | Official act, attachments, notification evidence and tax documents relevant to the request | Tax specialist |
| B: IMSS payroll | Authority, employer registration, workers and specified period | Official act, attachments, notification evidence, relevant payroll and affiliation changes | Payroll and social security specialist |
| Shared legal oversight | Type of act, representation and applicable route for each file | Complete document and notification and submission evidence, retained separately | Legal support for a resolution or inspection |
This allocation is a recommended control, not a requirement to hire particular professionals. Employers' duties to maintain records, including payroll, and handle registrations and changes appear in article 15 of the LSS. Select evidence relevant to the request: a collection of tax CFDI documents does not, by itself, replace requested salary or affiliation evidence.
Worked example: two letters, two files
Assume a business receives a SAT document requesting clarification of receipts connected with September VAT and an IMSS document concerning salary and affiliation for August during the same week. These are working assumptions; the precise type of act and response route have not yet been fully identified. The administrator opens case A under the RFC and September, and case B under the employer registration and August.
The tax specialist checks September receipts against the request. The social security lead reviews the relevant August payroll and affiliation changes. If both need a shared document, each folder retains an identified copy explaining its connection to that case. Attachments, periods and response dates are not automatically carried over from one file to the other.
Controls for handoff and follow-up
- Verify the document by entering the official portal address manually. Download the complete act, attachments and notification evidence; preserve the originals.
- Record the authority, subject, period, RFC or employer registration, assigned lead and file location separately. Confirm that the lead has accepted the assignment.
- Ask the specialist to verify the applicable deadline, representation and channel for the specific procedure. CFF articles 134 and 135 distinguish notification from its legal effects: there is no universal response period for every notice.
- Match each requested item to numbered attachments. After filing, retain the submission acknowledgment and an exact copy of what was sent in that case file.
- If the file reached the wrong person, escalate reassignment and verify the formal route before the applicable deadline. As an internal control, do not close the case based on an informal message or submission acknowledgment: check what evidence supports treating it as addressed.
The distinction between notification and legal effects comes from articles 134 and 135 of the CFF. Attachment indexes, acceptance by the assigned lead and closure criteria are operational recommendations, not general statutory requirements.
Frequently asked questions
Must every IMSS document be answered through its mailbox?
Do not assume so. Articles 286-L and 286-M of the LSS provide for electronic actions and notifications. Verify availability and the route for the specific procedure. SAT's Buzón Tributario is not Buzón IMSS.
Does emailing the files establish compliance?
An informal email to an adviser may document an internal handoff. It does not replace submission through the applicable route or evidence of that submission. Keep both records, recognizing their different functions.