Before comparing your expenses with the 35% deduction, check what each payment actually represents. An invoice for work on a property may cover maintenance or an improvement; a mortgage payment may combine principal and interest. This distinction matters for individuals under Mexico's ordinary rental income regime in Title IV, Chapter III of the Income Tax Law, not RESICO, lodging or subletting. Start with income actually collected, including amounts originally payable on credit (LISR, Articles 114 and 115).
The invoice should match the work actually performed
Publicación de InstagramMostrarOcultar
Original Fintax Instagram publication about deductible expenses when renting out property.
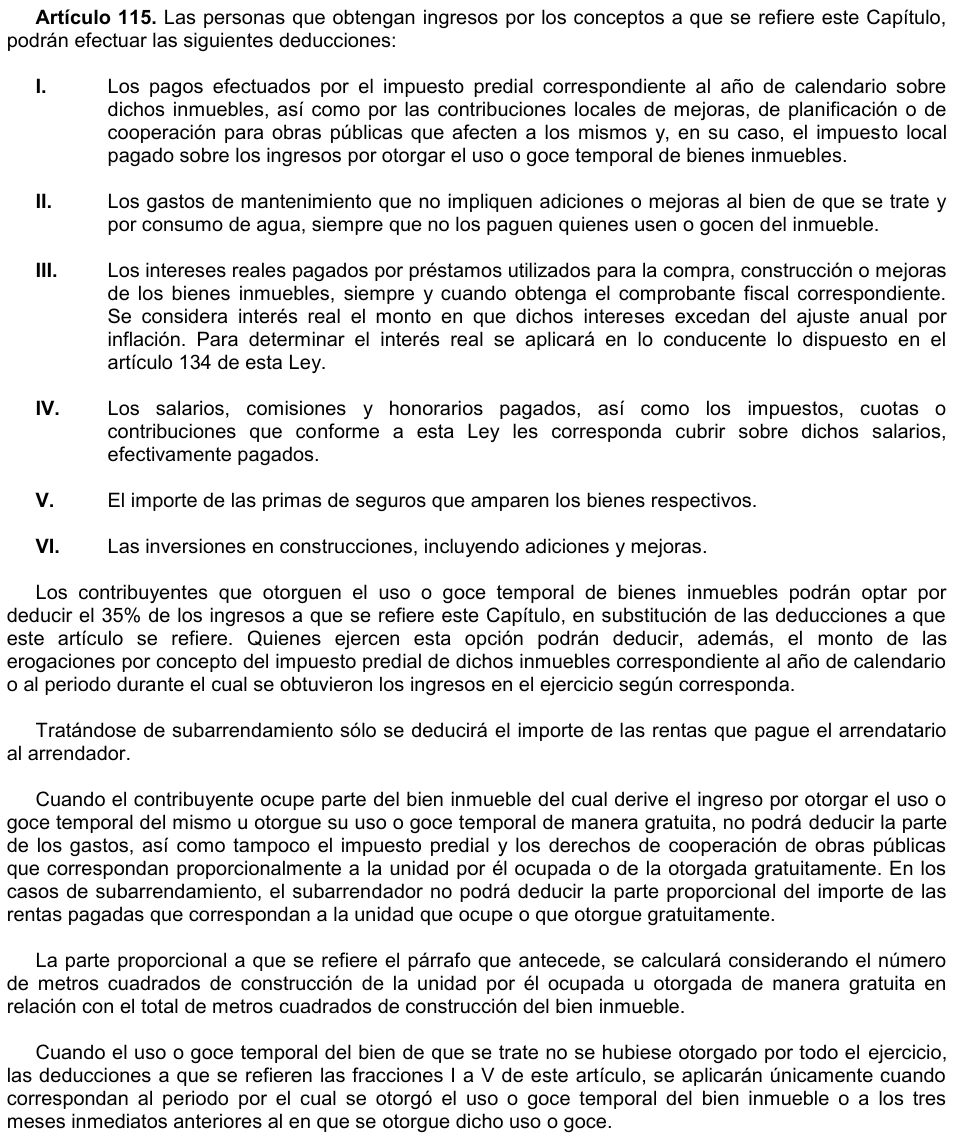
Article 115 allows deductions for maintenance that does not involve additions or improvements, and for water when the occupant does not pay it. It also covers insurance premiums and real interest, not mortgage principal or automatically the full nominal interest amount. Investments in construction, additions and improvements follow investment deduction rules: paying for the work does not make its full cost deductible as maintenance (LISR, Article 115).
As a recommended control, compare the invoice description with the contracted scope and photographs of the work. A generic description such as "work on property" cannot establish whether the work maintained the property or improved it. Request details before classifying the payment. This control helps document the transaction; it does not replace the applicable statutory deduction and documentation requirements in Article 147 of the LISR.
Example: classify six payments before adding them up
Assume an individual has one property, fully rented throughout the year, with annual rental income collected of MXN 240,000, excluding VAT. The following amounts are annual and relate to that property and period. The MXN 40,000 identified as actual deductible expenses already meets the applicable requirements. The owner paid for maintenance that contains no improvements. The real interest amount has been verified against bank and tax documentation.
The table separates cash paid from tax treatment, using the categories in Article 115 of the LISR. The suggested documents are controls for checking what was paid, alongside the applicable tax documentation.
| Payment | Annual amount | Treatment and evidence |
|---|---|---|
| Maintenance without improvements | MXN 18,000 | Verified deductible expense; compare the invoice, work scope and payment by the owner. |
| Real interest | MXN 12,000 | Verified deductible expense; review the bank statement or certificate and CFDI, rather than using all nominal interest. |
| Property insurance | MXN 6,000 | Verified deductible premium; check the policy, property covered and supporting document. |
| Property tax, or predial | MXN 4,000 | Deductible under actual expenses or additional to the 35% option; verify the property and period without counting it twice. |
| Mortgage principal | MXN 36,000 | Excluded from deductible interest; identify it separately in the bank's payment breakdown. |
| Building improvement | MXN 50,000 | Requires an investment deduction calculation; retain the invoice and scope without expensing the full amount as maintenance. |
What the comparison shows and what remains to be determined
Verified actual expenses total MXN 40,000: MXN 18,000 + MXN 12,000 + MXN 6,000 + MXN 4,000. Subtracting them from MXN 240,000 leaves MXN 200,000 before including the applicable investment deduction for the improvement. Neither the MXN 36,000 mortgage principal nor the full MXN 50,000 construction payment enters that expense total.
Under the 35% option, MXN 240,000 × 35% = MXN 84,000. Adding MXN 4,000 of property tax for the period produces a total deduction of MXN 88,000 and an illustrative base of MXN 152,000. The 35% replaces Article 115 deductions, except for the permitted additional property tax deduction. You cannot add the MXN 18,000 maintenance expense again (LISR, Article 115).
The comparison is not yet conclusive
These figures illustrate annual bases, not income tax payable or tax savings. Determine the investment deduction for the improvement and update the comparison. The 35% option is not a 35% discount on the tax.
A practical sequence for completing the review
- Classify each supporting document by its substance: maintenance, improvement, insurance, property tax or financing.
- Ask the bank for a principal and interest breakdown, and verify real interest against the tax documentation.
- Separate personal expenses; identify the property, who paid for maintenance or water, and the period covered by each amount.
- Calculate the investment deduction separately and reconcile property tax so it appears only once.
- Compare amounts for the same period and document the selected option, rather than choosing a different route each month.
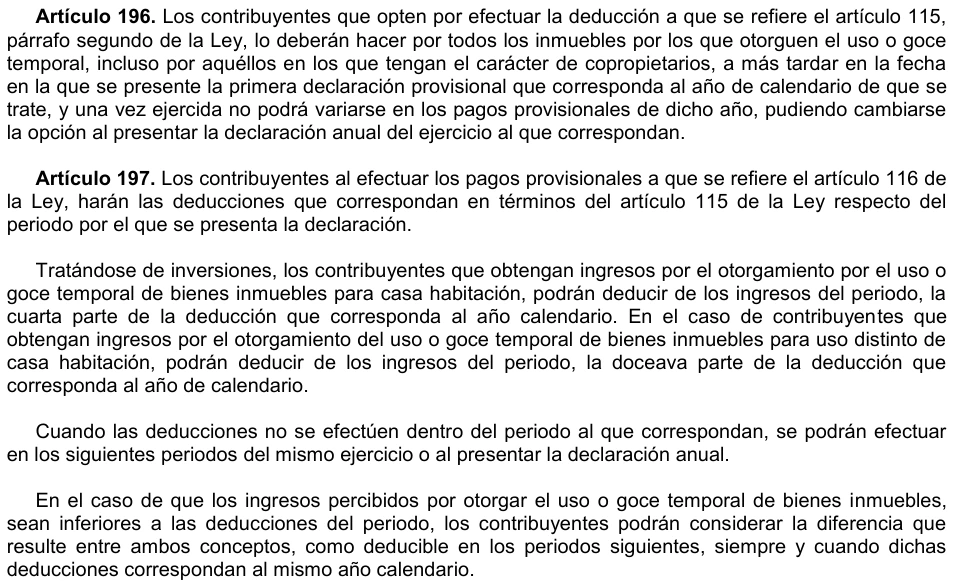
Those steps are recommended controls. The election rule is statutory: the 35% option covers all properties, including co-owned properties. It is elected with the first provisional payment of the year and cannot change during that year's provisional payments, although it may change in the annual return. Deductions and investment amounts must also follow the applicable period rules (LISR Regulations, Articles 196 and 197).
Frequently asked questions
Can I deduct the entire mortgage payment?
No. Separate principal from interest and verify deductible real interest with a CFDI. The total payment to the bank is not the deductible amount (LISR, Article 115).
Can I add maintenance to the 35% deduction?
No. That option replaces Article 115 deductions. Property tax for the period is the permitted addition, without counting it twice (LISR, Article 115).
Does the 35% option mean I can stop keeping records?
It is not an exemption from tax records. Keep income CFDIs, evidence of collections and property tax receipts. Relief from substantiating expenses for the 35% deduction does not make additional property tax deductible without support (LISR, Articles 114, 115 and 147).