A designer who invoices her own work, a store that carries inventory, and a company owned by three partners do not need the same structure. All three can sell and issue CFDI invoices, but they face different tax calculations, paperwork, and liability.
Separate the tax question from the operating question
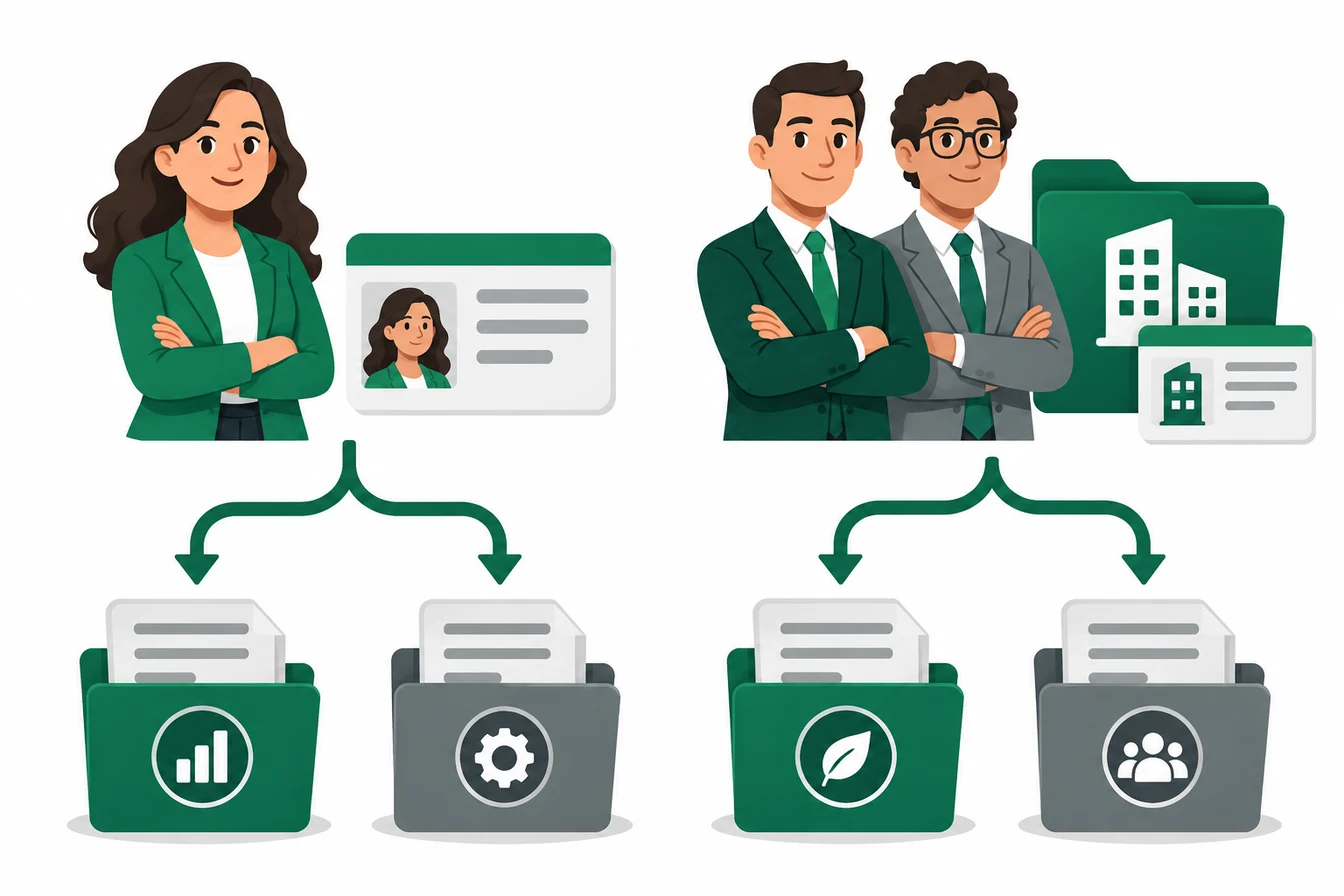
Entity choice affects more than the rate on a return. Review who signs contracts, who owns the assets, how money will be withdrawn, whether partners are involved and what liability the activity creates. Put those answers beside the tax estimate so the decision reflects the business that will actually operate.
People often mix up two separate decisions:
- Legal form. Operate under your own name as an individual or through a company with its own legal identity.
- Tax regime. Use RESICO, business activity, the general corporate regime or another applicable regime.
You can run a registered business as an individual or through a company. To compare the options, use your expected collections and expenses, identify who will own the business, and review the contracts it will sign. Calculate the tax under the applicable regimes before assuming incorporation will reduce it.
What changes between an individual and a legal entity
An individual taxpayer carries out economic activities under a personal RFC. An individual can provide services, sell products, lease property, and hire employees. A legal entity is a company or other organization, such as an S. de R.L., S.A. de C.V., or SAS, with its own RFC, accounts, and filing duties.
| Point | Individual taxpayer | Legal entity |
|---|---|---|
| Tax identity | Uses the person's RFC | Uses the company's RFC |
| Ownership | Has one owner | May have one or several owners, depending on the company type |
| Income tax | Depends on the regime; it may use progressive rates or RESICO rates | The general regime applies 30% to taxable profit |
| Deductions | Depend on the activity and regime; individual RESICO does not subtract them for income tax | Applies authorized deductions that meet statutory requirements |
| Liability | The owner is directly liable | Company and personal assets are separate, subject to legal exceptions |
| Administration | Can be simpler | Requires accounting, corporate records, and owner decisions |
A company may use the general regime or, if it qualifies, corporate RESICO. An individual can also have more than one activity and set of duties. Describe how the business operates first, then check which tax regimes apply.
When operating as an individual may be enough
An individual structure often fits when one person performs the work or runs the business, there are no investors, and the operation does not need corporate governance.
Consider this route if:
- clients are hiring your work directly;
- there are no partners or informal profit-sharing arrangements;
- contractual risk is limited;
- business expenses are low or fit the proposed tax regime;
- you can keep business cash in a dedicated account, even if the account remains legally yours.
RESICO may be available to individuals carrying out certain business, professional, or leasing activities. Article 113-E of Mexico's Income Tax Law sets an annual MXN 3.5 million income limit and calculates income tax on CFDI income actually collected, without deductions. A low rate therefore does not settle the question. A low-margin business may pay tax on a base far above its profit.
Ask both questions: "individual or company?" and "which tax regime, and why?"
When a company solves a real problem
A legal entity becomes useful when the business needs to exist apart from its founder. Revenue does not have to be large. Partners, investment, or a high-risk contract may justify a company much earlier.
These situations call for a closer look:
- two or more people will contribute cash, work, or intellectual property;
- an investor needs shares or equity interests;
- the business will sign leases, loans, or contracts with meaningful liability;
- it will employ staff on a recurring basis;
- clients or public tenders require a company as the contracting party;
- the owners need written rules for voting, representation, and profit distributions.
Limited liability helps, but it is not absolute. Personal guarantees, tax breaches, unlawful conduct, and other exceptions can expose owners, directors, or legal representatives. A poorly run company is not an automatic shield.
A SAS is one specific option
Mexico's Simplified Stock Corporation, or SAS, can be formed online by one or more individuals. The Ministry of Economy's SAS filing has no government fee and makes the use of a notary optional. Every shareholder needs an e.firma, and the company must meet ownership restrictions and the annually updated revenue ceiling.
Before forming a SAS, compare its restrictions with your plans for ownership and growth. An S. de R.L. or S.A. de C.V. may fit better if you need complex investment terms, custom owner rights or room to grow past the SAS limits. Review those needs with the person preparing the incorporation documents.
How to compare income tax without being misled by rates
The statement "a company pays 30%" is incomplete. Article 9 of Mexico's Income Tax Law applies the 30% rate to taxable profit, not gross revenue. Taxable profit takes taxable income, authorized deductions, paid employee profit sharing, and available tax-loss carryforwards into account.
Individual RESICO, by contrast, applies income tax to cash collected without subtracting deductions. A comparison needs at least the following inputs:
| Input | Why it matters |
|---|---|
| Amounts invoiced and collected | Regimes may recognize income at different times |
| Cost of goods and inventory | These amounts can change the actual margin |
| Payroll, rent, and suppliers | They show which expenses may qualify as deductions |
| Equipment and other investments | Their deductions may be spread across tax years |
| Owner withdrawals or dividends | Cash received by an owner can have an additional tax effect |
| VAT and withholding | They affect cash flow even though they are not the business's income tax |
Do not compare the structures solely by "2.5% versus 30%." Include the business tax, the cost of compliance, and the tax treatment of cash paid to its owners.
Corporate RESICO has its own eligibility rules
The revenue limit is only one test. Article 206 of the Income Tax Law covers Mexican resident legal entities owned solely by individuals when prior-year revenue does not exceed MXN 35 million, or when a new company expects to remain under that amount. It also contains exclusions involving ownership, control, and related parties.
A company does not qualify for RESICO merely because it invoices less than MXN 35 million. Its ownership and each exclusion need to be checked. The regime changes the timing of certain income and deductions, but it does not remove a company's accounting and filing duties.
Make sure the operation can handle the duties
Before choosing a structure, decide who will perform each task and where the data will come from:
- issue CFDI invoices and payment complements;
- reconcile bank transactions, collections, and invoices;
- submit monthly payments and annual returns;
- control VAT and withholding;
- run payroll and meet labor and social security duties;
- retain contracts, bank statements, and support for deductions;
- maintain ledgers, minutes, and powers of attorney for a company.
The DIOT information return may apply depending on the taxpayer's regime and registered duties. Check the SAT's DIOT guidance against the tax situation certificate and actual activity. It should not be assumed or dismissed without that check.
Signs the current structure no longer fits
Review the choice when:
- informal partners share a business that invoices through one person's RFC;
- operating costs are high, but the regime does not recognize them for income tax;
- personal spending and business collections use the same accounts;
- no one can say which contracts, assets, or debts belong to the business;
- registered activities no longer describe what the business sells;
- growth depends on credit, investment, or clients that require a company;
- monthly returns are prepared from incomplete records.
Identify the cause of each problem before changing the registration. Mixed bank transactions may need reconciliation and separate records; admitting a partner may require a review of the legal structure. Bring the relevant accounts or agreements to that review.
Build a file for the decision
Gather evidence before asking for a tax projection:
- invoices issued and cash collected during the past 12 months;
- sales and collection forecast for the next 12 months;
- expenses supported by CFDI, payroll, inventory, and investments;
- bank statements and business debt;
- current contracts and the risks they create;
- a list of owners, contributions, and agreements;
- the tax situation certificate and compliance opinion;
- filed returns, outstanding returns, and payments made.
With this file, an accountant can compare outcomes in pesos. The projection should state its assumptions, the added duties under each route, and the cost of maintaining the structure.
| Main fact pattern | Route worth testing |
|---|---|
| Personal services, few expenses, no partners | Individual in the applicable regime |
| High costs and a narrow margin | Compare regimes using actual income and deductions |
| Partners, investment, or voting rules | Legal entity with an owners' agreement |
| Contracts, employees, or asset exposure | Compare the responsibilities and costs of both structures before choosing |
Discuss the comparison with your adviser
Ask the adviser to explain how each option would affect the contracts you sign, the records you keep and the money you take out of the business. Keep the projection so you can revisit it when revenue, expenses or ownership change.
Fintax offers accounting plans for RESICO, individuals, and legal entities and a consultation to compare your case. The review should end with a documented route: tax regime, duties, compliance cost, and a date to reassess the choice.
Frequently asked questions
Which pays less tax in Mexico, an individual or a legal entity?
Legal form alone cannot answer that. The result depends on the tax regime, income, authorized deductions, and how owners receive profits. Compare the options with the business's actual figures.
Can an individual taxpayer hire employees in Mexico?
Yes. The individual must meet payroll, withholding, social security, labor, and tax duties. Having employees does not by itself require incorporation.
Is RESICO always best when the revenue is below the limit?
No. Staying below the revenue limit does not establish eligibility. Individuals must check the other restrictions and compare tax on collections without deductions against the other available regimes. Companies must also check ownership requirements and exclusions.
When should a business consider a legal entity?
Before admitting partners, accepting investment, signing major contracts, applying for credit, or separating business assets and risks from personal property.
Official links to complete the task
Open official services from a new browser tab, confirm the taxpayer and period, and save the resulting acknowledgment or evidence with the case.