If you keep your job and begin providing services independently, your first administrative decision is to check your current registration. Having an RFC for salary income does not mean the new services are already included. If your RFC exists, update its activities and obligations rather than obtain another one. Initial registration and updates are separate procedures under procedure sheets 1/CFF and 28/CFF in Annex 2 of the 2026 Miscellaneous Tax Resolution.
Choose the procedure based on your starting point
Publicación de InstagramMostrarOcultar
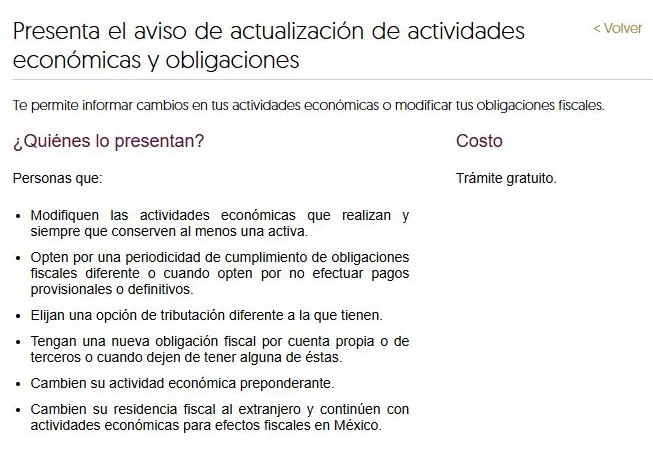
Original Fintax Instagram publication about tax registration when starting independent services.
Check your current registration before booking an appointment. As a recommended control, collect evidence of the service you will provide, when it began, and your income sources. This helps you answer the questionnaire accurately and identify a missing activity. The required procedure depends on whether you are already registered; additional documents for initial registration depend on your circumstances, under procedure sheets 1/CFF and 28/CFF in Annex 2.
| Current situation | Procedure | Before submitting | Completion evidence |
|---|---|---|---|
| RFC for salary income; starting services | Update under procedure sheet 28/CFF | Actual start date, activity, and income sources | Notice and transaction acknowledgment; review obligations |
| No RFC | Initial registration under procedure sheet 1/CFF | Appointment and applicable documents | Registration acknowledgment; review recorded details |
| Existing RFC, but activities are unknown | Check the record and determine the necessary update | Compare registration with actual work and income | Reviewed record and, if changed, transaction acknowledgment |
Update actual information and review before confirming
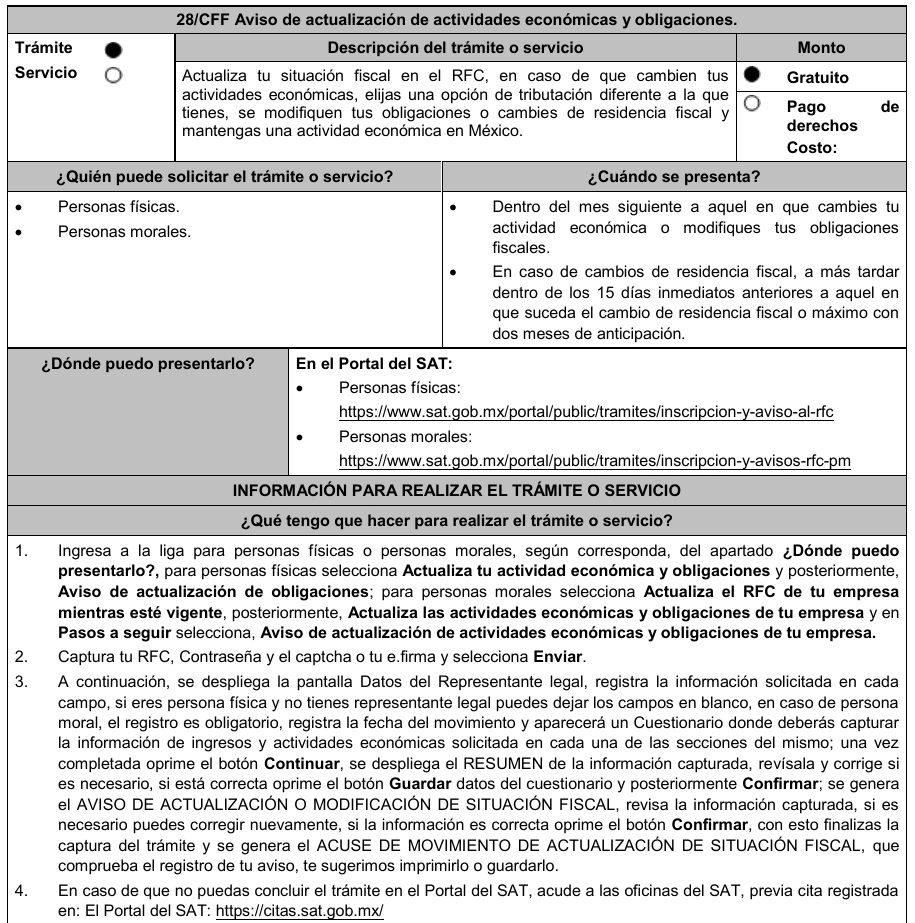
Procedure sheet 28/CFF allows online updates using your RFC and SAT password, or e.firma. The notice must be submitted within the month following the month in which activities change or obligations are modified. The process includes a questionnaire, information review, and confirmation to obtain the notice and transaction acknowledgment. These are procedural requirements, not optional recommendations: procedure sheet 28/CFF.
- Identify the actual start date and describe the service provided. If you have already received payment, include those transactions in your review.
- Answer the questionnaire using your actual activities and income sources, including the job you are keeping.
- Review the summary before confirming: RFC, date, activity, tax regime, and obligations should match your circumstances.
- Save the notice and acknowledgment. As a recommended control, compare the result with the reviewed summary and record upcoming compliance dates based on the actual obligations.
Providing independent services does not automatically place you in RESICO. Eligibility depends on Article 113-E, including its income limit, compatibility with other income, and applicable exclusions. If you keep receiving a salary, include it in that review; an attractive regime is not sufficient grounds for selecting it. Verify the appropriate income-tax regime before confirming, under Article 113-E of the Income Tax Law.
Example: Mariana keeps her job
Assume Mariana already has an RFC for salary income, keeps her job, and begins independent translation services on September 5, 2026. That is her actual start date. Her administrative step is to update her RFC under procedure sheet 28/CFF, not register again. Before submitting, she reviews the translation activity and regime eligibility, taking her salary into account. The general filing period is the month following the change: procedure sheet 28/CFF.
Mariana downloads the acknowledgment and checks that it reflects her services and salary situation. If she has already received payment, she records the date, client, service description, and amount as a transaction control; she does not replace the actual start with a future date. She then organizes receipts and the resulting obligations. The control helps align actual activity, registration, and invoicing under Articles 27, 29, and 29-A of the Federal Tax Code.
If you have no RFC, prepare for registration
Raúl, by contrast, has no RFC. Procedure sheet 1/CFF provides for in-person registration with an appointment, original proof of address, and valid official identification; he must check the CURP condition and applicable additional documents. He can book through SAT's official appointment portal. Virtual registration under procedure sheet 3/CFF is limited to specific circumstances, such as salary-only income or no obligations; it is not the general route for independent services. See procedure sheets 1/CFF and 3/CFF.
Complete the procedure and prepare a real CFDI
The SAT password and e.firma have separate procedures, 12/CFF and 14/CFF; obtaining an RFC does not automatically issue them. If you request e.firma during the same registration visit, prepare a USB drive and the requirements in procedure sheet 14/CFF. Also verify which credential and, where applicable, digital seal certificate your chosen invoicing tool requires: they are not interchangeable. Source: Annex 2.
For your first CFDI, use a real transaction and verify issuer and recipient information. Collect the recipient's RFC, name, postal code, tax regime, and CFDI use according to SAT's required invoicing data. Recommended controls include encrypting credential files, never posting keys publicly, and keeping the acknowledgment, supporting documents, and payment records together.
Frequently asked questions
Do I need another RFC if I am already an employee?
No. Update the existing registration to reflect your services and corresponding obligations under procedure sheet 28/CFF.
Does having an RFC mean I am finished?
No. Check that your registration matches your activity and prepare the means to issue CFDIs. Saving a PDF without checking its contents does not replace that review: Federal Tax Code, Articles 27, 29, and 29-A.